Key Points
- Liquidia insiders have sold shares amid a patent settlement and analyst price-target cuts, though institutional buying and rising YUTREPIA sales offer some offsetting support.
- Brinker International insiders sold heavily during a successful Chili's turnaround, but strong sales growth, margin gains, and analyst optimism suggest the sales are less concerning.
- Procter & Gamble's insider sales appear tied to routine prearranged trading plans, with analysts bullish on the stock and the company maintaining strong cash flow and dividend growth.
Insider trading sends many signals, but not all of them are what they seem.
Insider selling can be a green light for investors or a warning to stay away; it depends on the market. Sector trends, the business cycle, and a company's profit outlook all influence how investors should interpret those transactions. All else being equal, profitable companies are more valuable than those that aren’t, separating true investments from speculation and risk.
Liquidia Insiders Liquidate After Bad News
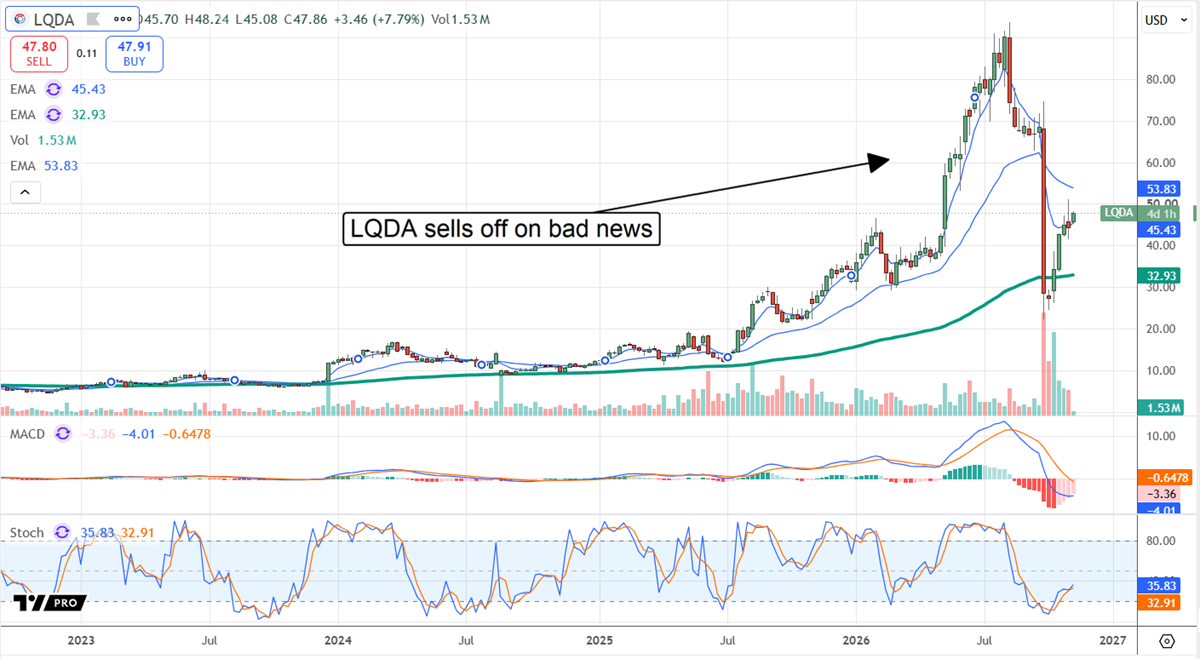
Liquidia (NASDAQ: LQDA) is a commercial-phase biopharma company that reported bad news this year. Its primary treatment, YUTREPIA, faced a setback after a September patent ruling, but an October settlement with United Therapeutics resolved the litigation. Liquidia can continue selling YUTREPIA for pulmonary arterial hypertension, although it must stop promoting the drug for a separate indication and make substantial settlement payments. The agreement creates financial challenges, but the company's growing sales provide some relief. In Q3, YUTREPIA sales climbed 31% sequentially to $222.7 million, even as Liquidia recorded a $389.7 million charge related to the settlement.
To make matters worse, insiders are selling into the correction, helping depress shares.
Insiders own 25% of LQDA shares and are a significant force, with at least nine executives with Chief in their title selling since the patent court ruling. Prearranged trading plans account for some of these sales, allowing executives to capitalize on high share prices and manage share-based compensation. However, not all transactions fall under these plans. Many of these trades are open-market sales, suggesting a top-heavy managerial team may be trimming excess risk.
Wall Street's outlook for Liquidia has weakened, adding to the stock's challenges.
Many analysts have slashed their price targets in recent months, reflecting growing concerns about Liquidia's outlook. Shares traded well below the $72.85 consensus target in early November, although that gap also suggests potential upside if the company's operating performance continues to improve.
Institutions own about 65% of Liquidia shares, but institutional buying has exceeded selling over the past 12 months. Despite the recent insider selling, institutional support and improving sales could help offset some of the stock's downward pressure.
Chili’s Insiders Reap Rewards of Successful Turnaround
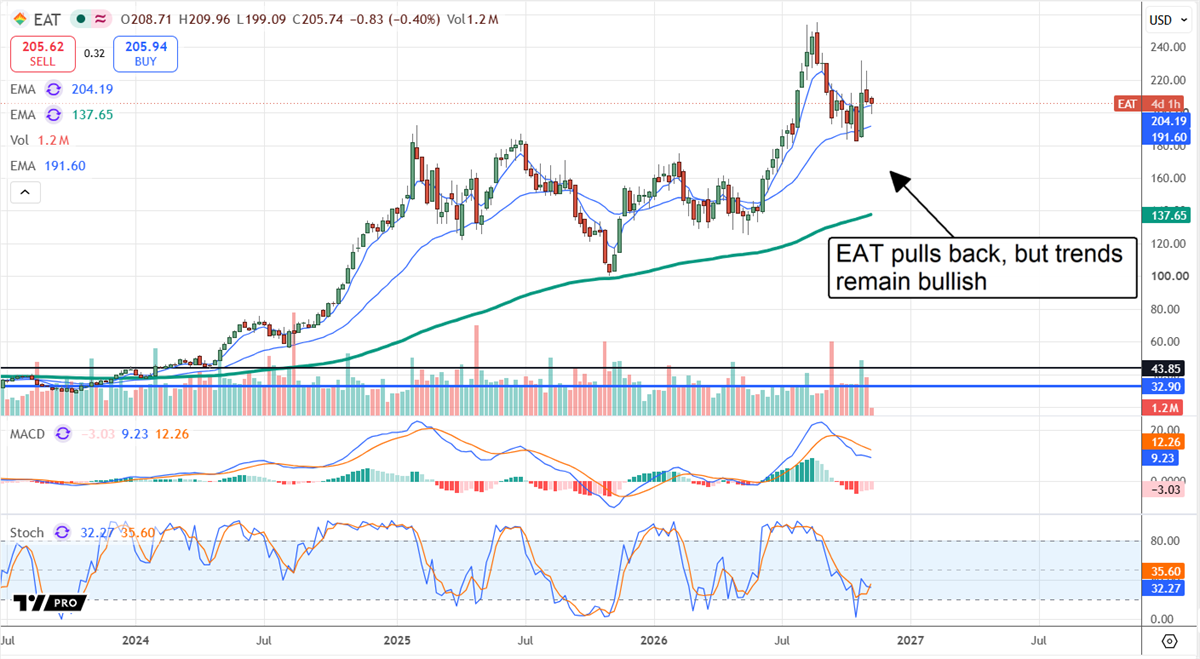
Chili’s parent company Brinker International (NASDAQ: EAT) saw heavy insider selling in Q3 and early Q4, but the company's strong operating performance suggests those sales may be less concerning than they initially appear.
The sales came after two years of improving results, strong comparable sales, and margin gains tied to a strategy shift. Chili's has embraced a “better-than-fast-food” approach, offering value meals and beverages that resonate with consumers. The strategy has helped drive sustained sales growth, widening margins, and accelerating earnings, with Chili’s sales up more than 50% in the three-year stack.
Analysts like what they are seeing from EAT. Coverage has increased, sentiment has strengthened, and price targets have climbed, supporting the stock's Moderate Buy consensus rating. The average price target is up more than 50% over the past 12 months, and implies more than 20% from October’s lows. Reaching that target would put shares at a fresh all-time high.
The fiscal Q2 results due in early 2027 could provide another catalyst for analysts to raise their targets if the company's momentum continues.
Institutions own approximately 99% of EAT shares and have been net buyers this year, signaling confidence in the company's turnaround. The risk is that they distributed shares in early Q4 and may continue to do so, limiting upside until the FQ2 release. Improving performance at non-core brands, expanding margins, strong cash flow, and sustained comparable sales growth could encourage institutions to increase their holdings.
Procter & Gamble Insider Sales Raise Few Red Flags
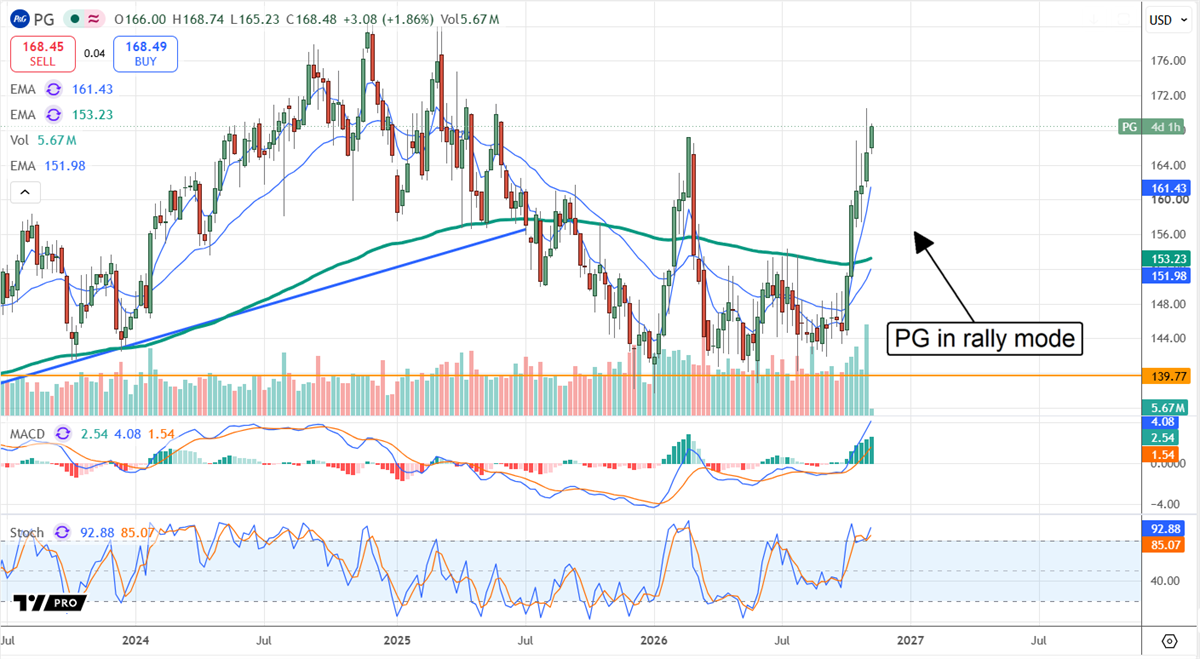
Insider selling of Procter & Gamble (NYSE: PG) shares is not a red flag. The spotty, sometimes large, share sales are linked to prearranged trading plans, intended to maintain diversification and manage options exercises tied to share-based compensation.
Executives still own a significant stake, while the company's established business and strong cash flow help offset ongoing cost pressures.
The main hurdle for Procter & Gamble is consumers shifting to cheaper alternatives, which could pressure sales and profitability. However, the company's broad product portfolio gives it an advantage, allowing it to serve budget-conscious consumers without relying solely on premium-priced products.
Analysts are bullish on PG stock. Of the 26 analysts covering Procter & Gamble, 15 rate it a Buy and 11 a Hold, giving the stock a Moderate Buy consensus rating. Price targets have also climbed, with the average around $170. Continued upward revisions could signal greater confidence in the company's outlook and support further share-price gains.
Investors should consider Procter & Gamble’s cash flow and profitability, which support healthy capital returns. Capital returns include share buybacks and dividends, including distribution growth.
The company is a Dividend King, yielding around 2.6%, and able to sustain annual distribution increases for the foreseeable future.
Procter & Gamble's acquisition of Thorne HealthTech could drive growth by expanding its presence in premium, practitioner-focused, subscription-based healthcare. However, rising input costs have already pressured margins, and further increases could weigh on profitability.
Companies in This Article:
| Company | Current Price | Price Change | Dividend Yield | P/E Ratio | Consensus Rating | Consensus Price Target |
|---|
| Brinker International (EAT) | $194.48 | -0.3% | 0.78% | 17.12 | Moderate Buy | $249.80 |
| Liquidia (LQDA) | $53.68 | +4.4% | N/A | 39.29 | Hold | $77.31 |
| Procter & Gamble (PG) | $166.83 | -1.1% | 2.61% | 25.13 | Moderate Buy | $170.57 |
Experience
Thomas Hughes has been a contributing author for InsiderTrades.com since 2019.
- Professional Background: Thomas Hughes is the Managing Partner of Passive Market Intelligence LLC, a market research platform he launched in 2023 with the mission: “We watch the market so you don't have to.” He has worked as a blogger, stock market commentator, and independent analyst since 2010 and has been actively involved in trading and investing since 2005.
- Credentials: He holds an Associate of Arts in Culinary Technology—training that honed his discipline, attention to detail, and ability to anticipate outcomes, all of which carry over into his work as a market analyst.
- Finance Experience: Thomas has been writing about finance and investing since 2011, when he discovered it could be more than a personal passion—it could be a profession. He’s been a contributing writer for InsiderTrades.com since 2019.
- Writing Focus: He specializes in the S&P 500, small-cap stocks, dividend and high-yield strategies, consumer staples, retail, technology, oil, and cryptocurrencies. His analysis blends chart-based technical setups with key fundamental insights, helping readers identify actionable trends.
- Investment Approach: Thomas takes a hybrid approach that combines technical analysis with deep fundamental research. He often writes about macroeconomic shifts, earnings trends, and sentiment-based trading signals.
- Inspiration: Thomas first became interested in stocks after attending a seminar on how to buy and sell your own shares. That event opened his eyes to the market's potential and sparked a lifelong interest in investing.
- Fun Fact: Thomas took up model railroading by accident a few years ago—and now he can’t stop running the rails.
- Areas of Expertise: Technical and fundamental analysis, S&P 500, retail and consumer sectors, dividends, market trends
Education
Associate of Arts in Culinary Technology
