Key Points
- Insider selling across CoreWeave, Arista Networks, Dell, Snowflake and NVIDIA does not necessarily signal weakening fundamentals or bearish outlooks for these AI-linked stocks.
- CoreWeave faces the most risk due to heavy debt and interest-rate exposure, though analysts still rate it a Moderate Buy with substantial upside.
- Analysts remain broadly bullish on Arista Networks, Snowflake, and NVIDIA, citing strong fundamentals, growing AI demand, and significant price target upside.
The AI trade has headwinds, and none as potentially alarming as insider selling. The question, however, is what other forces are in play, and how they affect the stock price outlook. While insider selling is a headwind, it isn't always a red flag. If stock prices are favorable, analysts and institutions are supportive, and the fundamentals are strong, insider selling is nothing more than a detail.
CoreWeave Insiders Drive Shares to Long-Term Lows
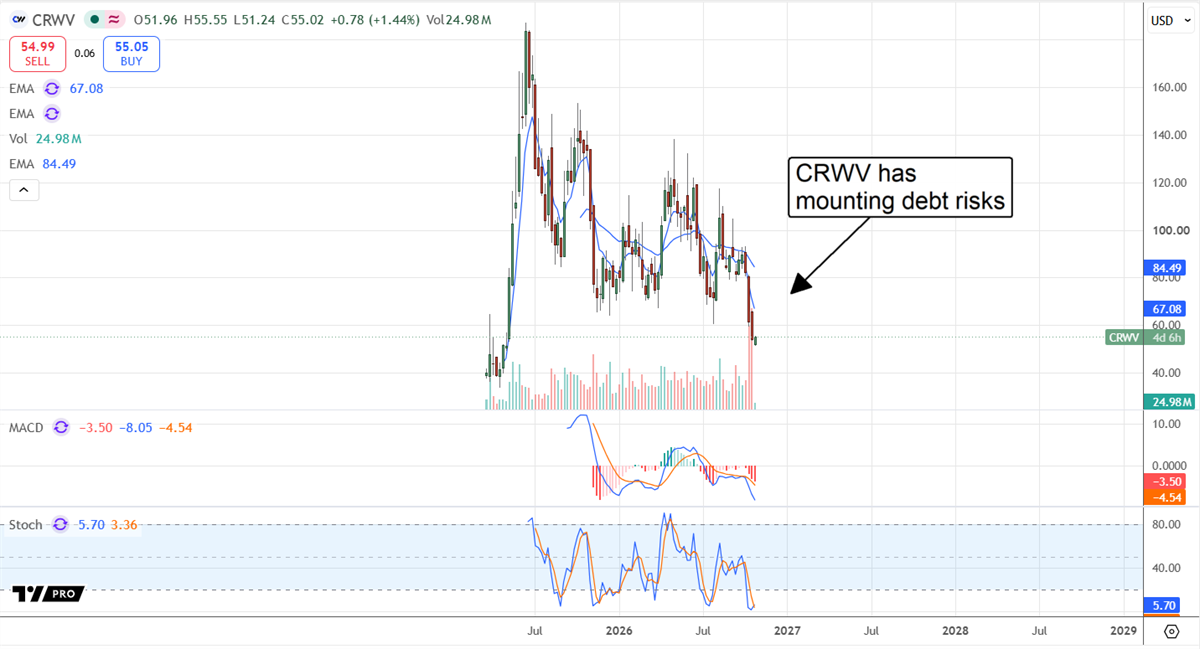
CoreWeave (NASDAQ: CRWV) insiders have been selling shares for several quarters, with founders and early investors taking advantage of high share prices to trim down holdings. Key details include over 20% insider ownership tied to founding executives and continued selling in Q4 2026. With shares down at long-term lows, insider sales are salt in an open wound regardless of their nature.
The risk with CoreWeave, however, isn’t so much the insider selling as it is the debt. The company is the leading neocloud in interest-rate exposure, and the risks are mounting. Already in junk status, the company faces an incredibly high cost of translating backlogs into revenue, which is affecting its outlook.
Analysts have been trimming their price targets, capping gains. However, 36 analysts rate the stock a consensus Moderate Buy, with approximately 125% upside to the average price target. In this scenario, given the oversold price action, a positive catalyst could trigger significant upside.
Arista Networks: The Fabric of AI
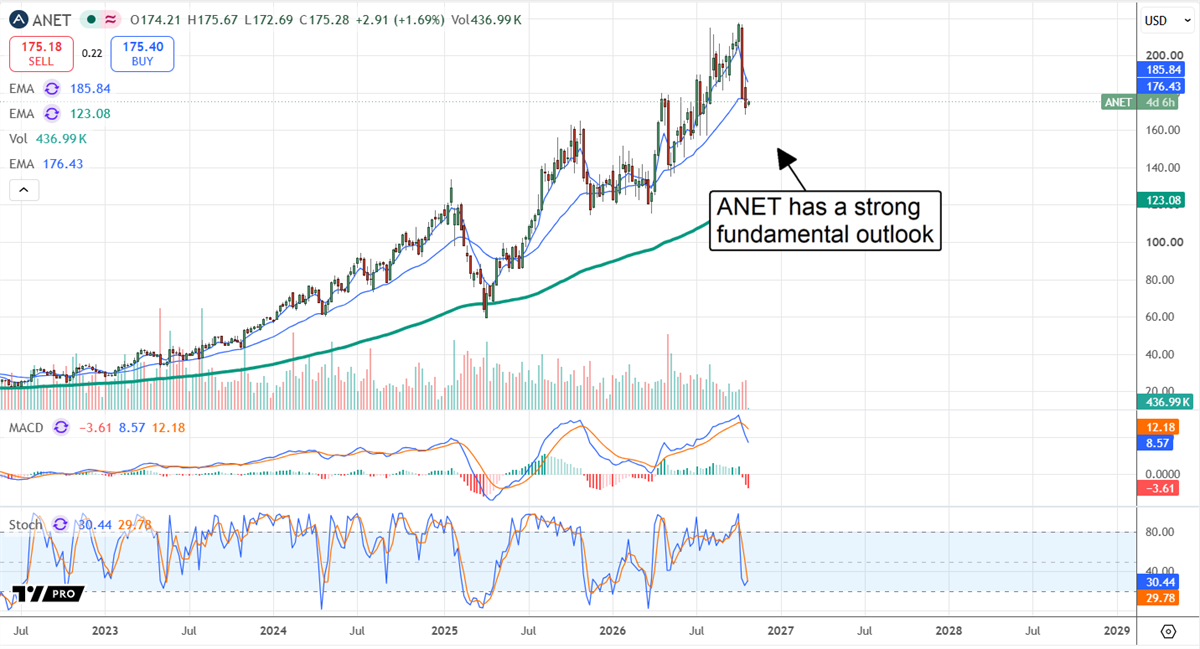
Arista Networks (NASDAQ: ANET) is critical to AI infrastructure because of its Ethernet switches, routing, and fabric technologies. Once a simple layer of the technology stack, these technologies are now essential for high-speed, high-efficiency operation.
The shift has put ANET products in high demand, and the stock price is rising. This provides incentive for insiders to sell, and they are doing so en masse. InsiderTrades tracks Q3 sales from the CEO, CFO, COO, and CTO, along with several directors. The caveat is that the sales were primarily under prearranged plans, and the company's fundamental story is unchanged.
Analysts rate ANET as a consensus Buy because of its growing importance. The company is helping break the NVIDIA (NASDAQ: NVDA) InfiniBand monopoly, opening the door for a wider range of choices based on open standards. The consensus price target forecasts more than 30% upside, and institutions are accumulating.
Dell: Early Investors Monetize Their Investment
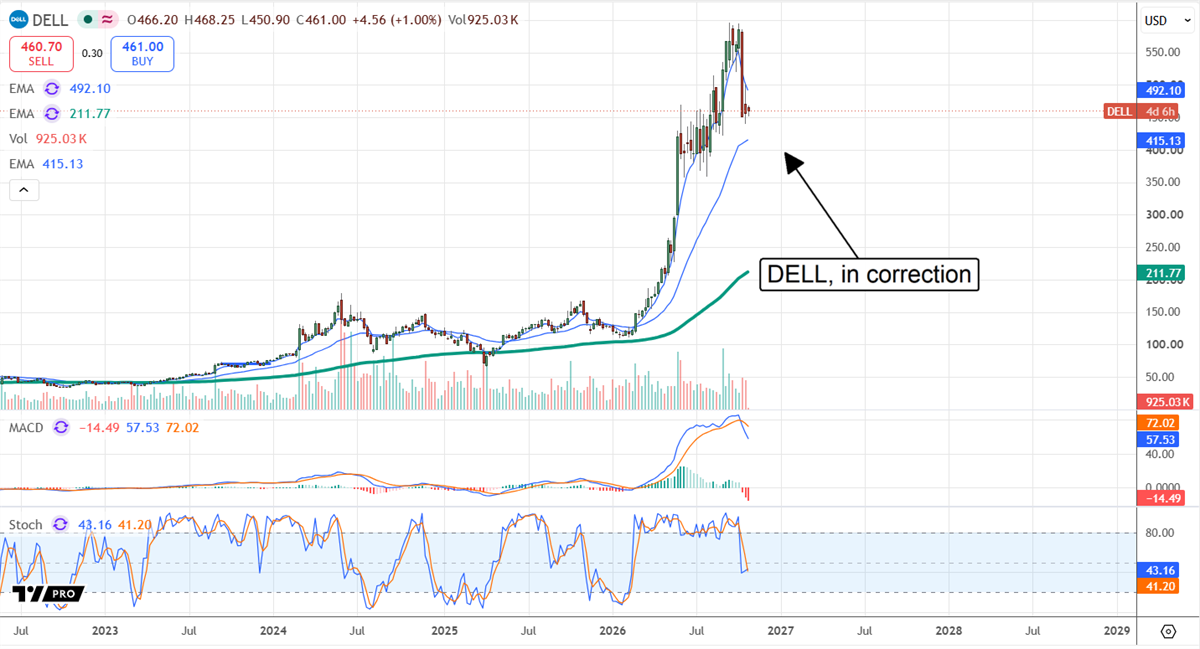
Dell’s (NYSE: DELL) insiders are selling for a good reason: the stock is up more than 250% this year, providing an irresistible opportunity to monetize shares. The primary seller is Silver Lake Partners, which has been liquidating its position for several quarters. The likely outcome is continued selling, and gains may be capped.
DELL shares hit a peak in early October and are now in correction. The initial fall was substantial, more than 25%, suggesting an extended consolidation with a risk of deeper pullback. Institutional activity has also been iffy, with the group distributing on balance in early Q4.
Snowflake: The Melt-Up Isn’t Over Yet
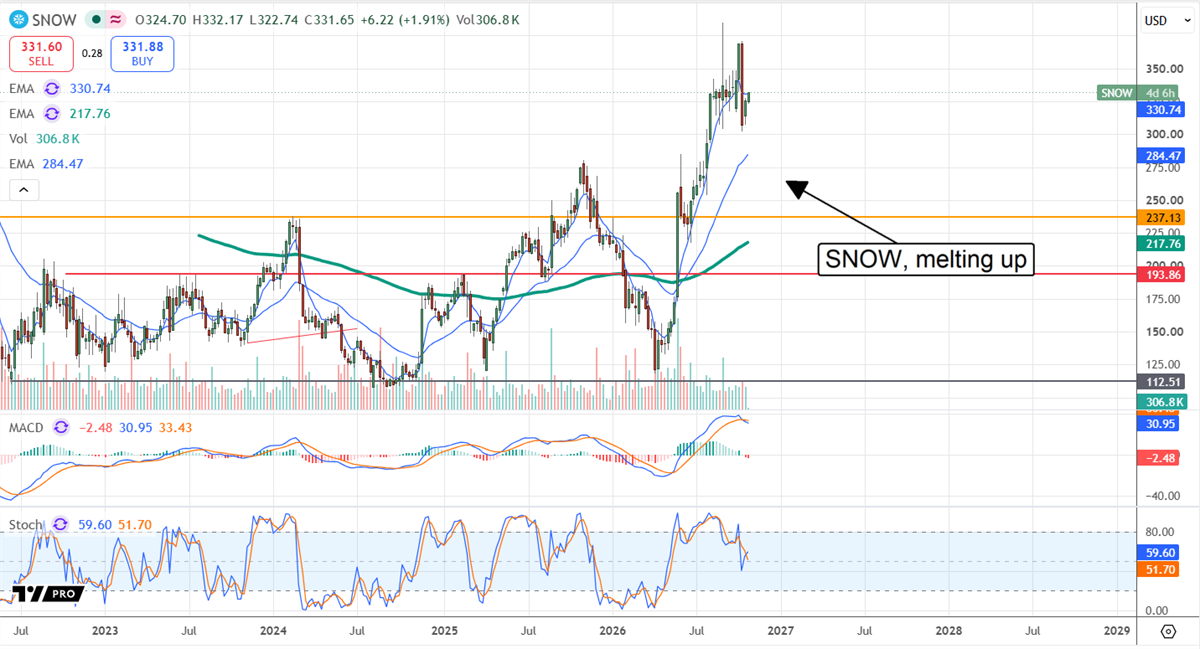
Snowflake’s (NASDAQ: SNOW) stock price is in melt-up mode following a misinterpreted AI SaaS apocalypse. The late-2026 narrative is that agentic AI doesn't erode demand—it drives it, and has the business performing at the high end of expectations. Insiders who are selling include numerous directors and junior executives with years of tenure and shares to sell.
The offset is that analysts' trends remain bullish, with coverage up, a bullish bias to the Moderate Buy rating, and about 25% upside. Institutional trends are also bullish, subdued compared to the prior year, but with buying outweighing selling.
Snowflake's primary growth catalyst is its transition to an agentic AI platform and consumption. Because the company operates on a consumption-based model, continued growth depends on attracting new customers and expanding usage among existing ones.
NVIDIA: The Center of AI Cash Flow
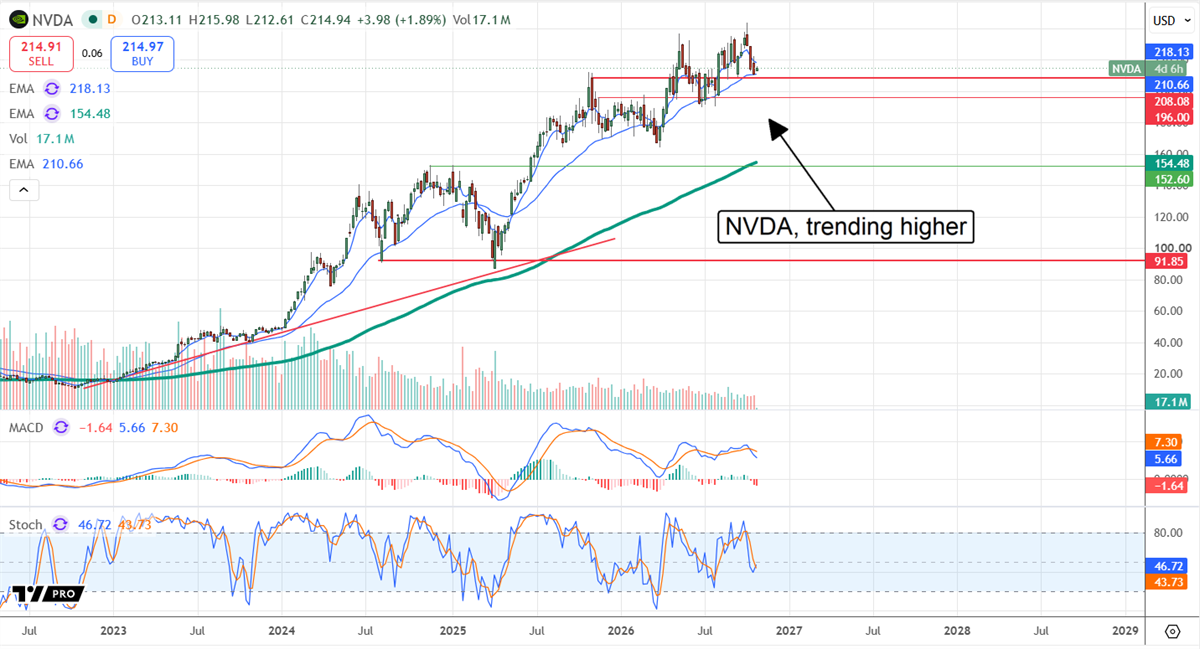
Most AI spending is funneling toward NVIDIA, its GPUs, full-stack of products, software, and services, making it the single-most important AI stock. The company looks poised to more than double over the coming years, with growth underpinned by an expanding ecosystem, including physical AI and robotics.
Insiders sold NVDA stock in Q3, including directors, an EVP, and the CFO, but investors shouldn’t worry too much. Selling is down overall, and the fundamental outlook is unchanged, though it still carries risk.
The biggest risk is capital and the time it takes to monetize backlogs, which has strained the entire industry. The likely outcome is that spending plans remain unchanged, but headwinds will persist until monetization becomes more evident across the AI ecosystem. When that happens, capital flow will depend less on balance sheet or third-party financing, allowing risk-on sentiment to regain control. Analysts rate NVIDIA as a consensus Buy and see it advancing 50% within 12 months.
Companies in This Article:
| Company | Current Price | Price Change | Dividend Yield | P/E Ratio | Consensus Rating | Consensus Price Target |
|---|
| CoreWeave (CRWV) | $56.73 | +4.6% | N/A | -15.56 | Moderate Buy | $128.78 |
| Arista Networks (ANET) | $179.02 | +3.9% | N/A | 56.38 | Buy | $233.20 |
| Dell Technologies (DELL) | $472.31 | +3.5% | 0.53% | 27.37 | Moderate Buy | $569.96 |
| Snowflake (SNOW) | $333.72 | +2.5% | N/A | -104.94 | Moderate Buy | $413.87 |
| NVIDIA (NVDA) | $216.30 | +2.5% | 0.46% | 27.33 | Buy | $321.47 |
Experience
Thomas Hughes has been a contributing author for InsiderTrades.com since 2019.
- Professional Background: Thomas Hughes is the Managing Partner of Passive Market Intelligence LLC, a market research platform he launched in 2023 with the mission: “We watch the market so you don't have to.” He has worked as a blogger, stock market commentator, and independent analyst since 2010 and has been actively involved in trading and investing since 2005.
- Credentials: He holds an Associate of Arts in Culinary Technology—training that honed his discipline, attention to detail, and ability to anticipate outcomes, all of which carry over into his work as a market analyst.
- Finance Experience: Thomas has been writing about finance and investing since 2011, when he discovered it could be more than a personal passion—it could be a profession. He’s been a contributing writer for InsiderTrades.com since 2019.
- Writing Focus: He specializes in the S&P 500, small-cap stocks, dividend and high-yield strategies, consumer staples, retail, technology, oil, and cryptocurrencies. His analysis blends chart-based technical setups with key fundamental insights, helping readers identify actionable trends.
- Investment Approach: Thomas takes a hybrid approach that combines technical analysis with deep fundamental research. He often writes about macroeconomic shifts, earnings trends, and sentiment-based trading signals.
- Inspiration: Thomas first became interested in stocks after attending a seminar on how to buy and sell your own shares. That event opened his eyes to the market's potential and sparked a lifelong interest in investing.
- Fun Fact: Thomas took up model railroading by accident a few years ago—and now he can’t stop running the rails.
- Areas of Expertise: Technical and fundamental analysis, S&P 500, retail and consumer sectors, dividends, market trends
Education
Associate of Arts in Culinary Technology
