Key Points
- Insiders at H.B. Fuller, FocalTherics, and Cardinal Infrastructure Group bought shares, signaling potential price floors and recovery opportunities.
- H.B. Fuller, a Dividend King trading near 52-week lows, shows improving profitability, institutional buying, and analyst targets suggesting roughly 30% upside.
- FocalTherics and Cardinal Infrastructure Group face near-term headwinds, but insider buying, analyst upside forecasts, and strong institutional ownership suggest deep value opportunities.
Insider buying is a signal for investors, but not always a good one. Sometimes insiders buy on faith, and yet the company continues to struggle. The question is whether the rest of the market agrees, because if it does, the opportunity is real. In this scenario, insider buying often signals a floor or, at least, the potential for a bottom and reversal, compounding already bullish trends. Assuming those trends are sustained, the likely outcome is stock price recovery, sustainable rallies, and fresh highs over time—a recipe for market-beating total returns.
H.B. Fuller Insiders Signal Floor for Market
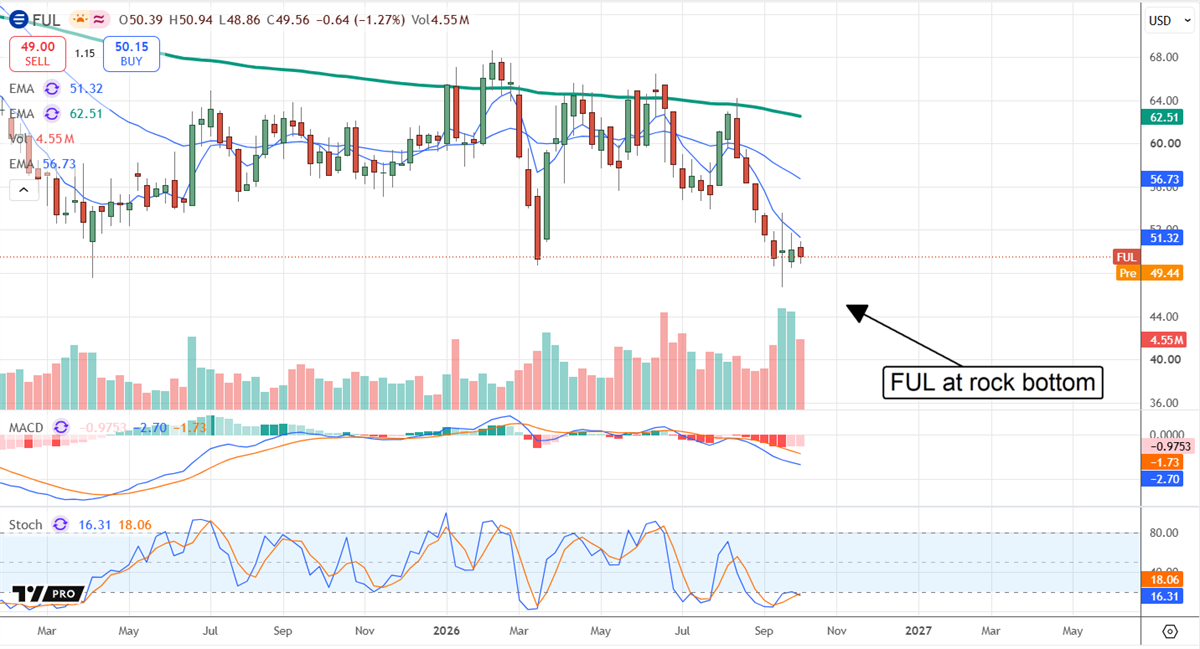
H.B. Fuller (NYSE: FUL) insiders went on a buying spree in late September, buying more than $600,000 in shares. Drivers include 52-week low share prices, improving corporate profitability, confidence in the strategy, and the dividend.
The dividend is the core of the opportunity, as H.B. Fuller is a Dividend King with the capacity to sustain its streak for another 50 years. The company’s adhesives and sealants business is growing, acquisitions are in the works, and payout metrics are very attractive. The yield isn’t abnormally high but solid at 2%, about double the broad market S&P 500 average. It is increasing at a modest annual pace, and the payout ratio is less than 30% of the earnings forecast.
Analysts and institutional trends reinforce the view that this stock has bottomed. Institutions own about 96% of the stock, reflecting a high confidence in its cash-producing and capital-returning ability, and have bought aggressively this year. Analysts, meanwhile, have moderated their price targets but only marginally, with coverage and sentiment firming and Q3 price targets aligned with the consensus. It forecasts about 30% upside, which is likely conservative.
H.B. Fuller has headwinds today but remains on track to sustain returns, including share buybacks. Buybacks reduce the count incrementally each quarter, helping investors build leverage. The likely outcome is that FUL shares revert to their secular-grade uptrend, which remains intact and presents an attractive entry for long-term total-return investors.
FocalTherics Insiders Highlight Robotic Opportunity
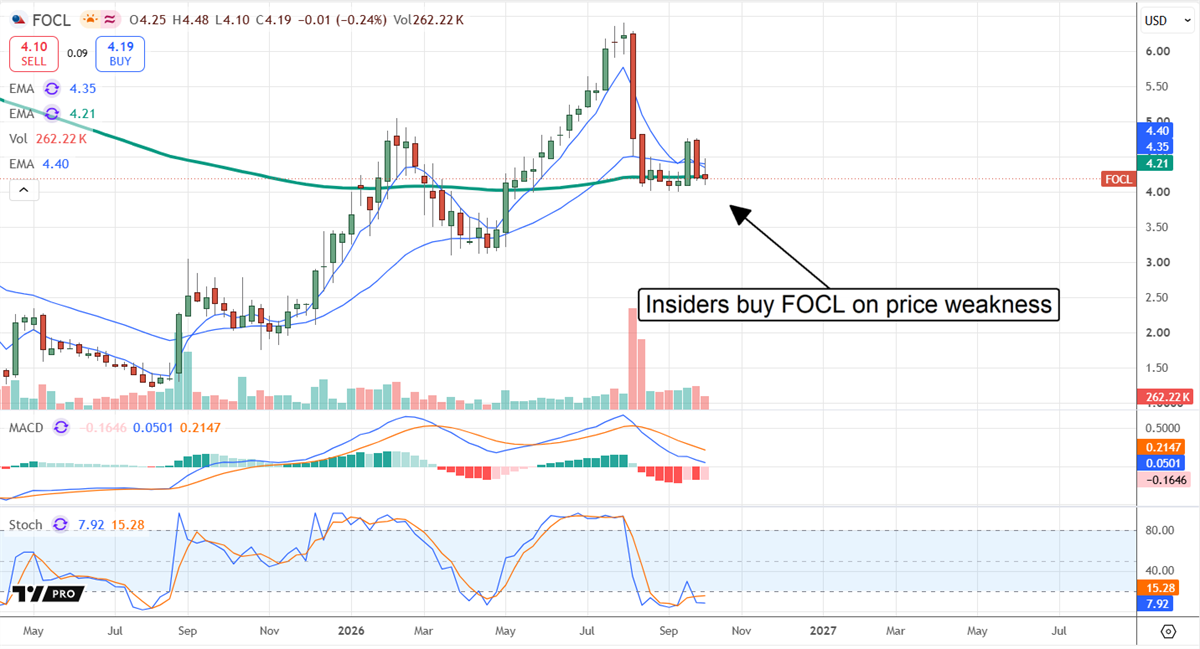
FocalTherics (NASDAQ: FOCL) insiders conspicuously bought shares in Q3 following years of inactivity. Their buying highlights a growth opportunity underpinned by robotic surgical technology, new partnerships, and optimism about future profitability.
The core technology is Focal One Robotic HIFU (High-Intensity Focused Ultrasound). It is approved in the U.S. for several indications, including prostate cancer, and internationally for endometriosis. Revenue growth is spotty now due to legacy products, but is expected to revert to a strong positive in the coming year, with profitability by the end of the decade.
Analysts and institutional activity reflect the strengthened opportunity. Institutions own about 63% of the stock and are buying in 2026, while analysts' sentiment is perking up. Only five analysts with active ratings on the stock are tracked, but four of those ratings are fresh. These analysts rate FOCL a consensus Hold and see it rising 85% from mid-October trading prices.
A 85% move would bring this stock to multiyear highs and signal an inflection point. Assuming business momentum continues, the stock could reach these highs, opening the door to a larger movement and potentially reclaiming the $12 level within the next few years.
Cardinal Infrastructure Group: Deep Value in Wake of IPO
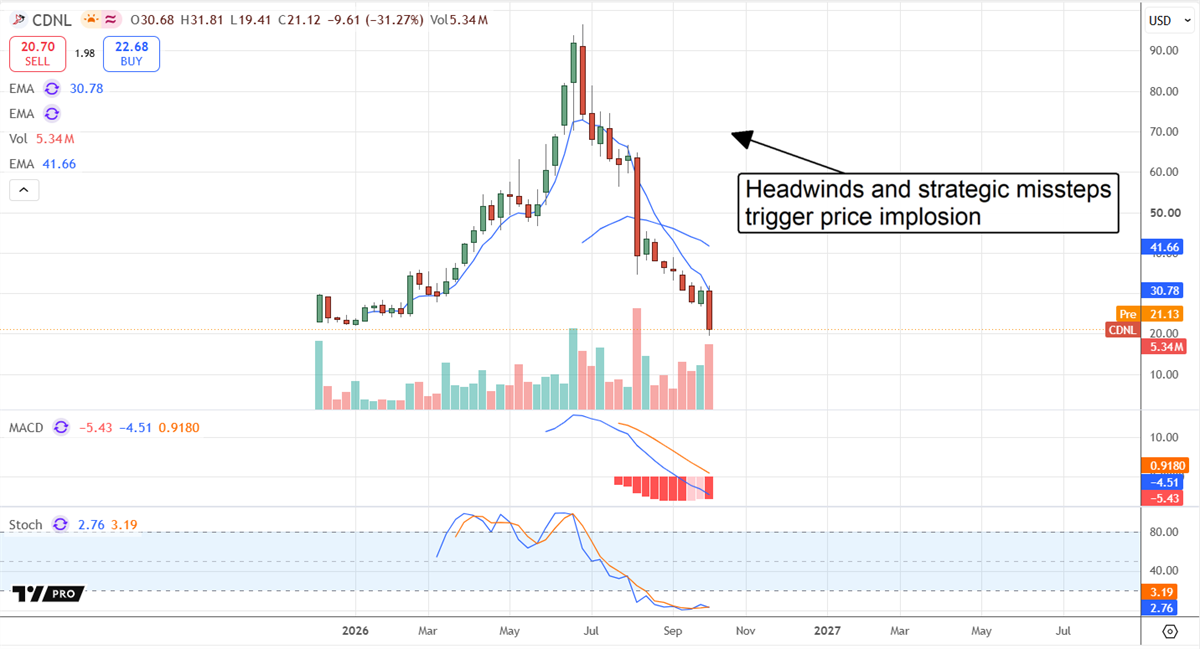
Cardinal Infrastructure Group (NASDAQ: CDNL) insiders are actively buying shares following a massive share price drop. Their activity highlights deep value, as the price drop does not reflect the growth opportunity. Near-term headwinds include margin contraction; however, it's tied to an acquisition that will drive growth and wider margins over time. Q3 buyers include the CEO, COO, and several directors.
Analyst and institutional activity underscores the value opportunity in Q4. Analyst coverage is light; only six are tracked, but they rate the stock a Moderate Buy, see it rising more than 130% to the consensus. Additionally, October price action is well below even the lowest analyst price target. Institutions, meanwhile, own more than 90% of the stock and have bought on balance this year. The risk is that this group started selling in Q3 and may keep the market under pressure until headwinds ease and clarity improves.
The market gets CDNL wrong in assuming that the company's headwinds are long-lasting. The headwinds are tied to its growth potential: the backlog is too big to handle. Cardinal had to outsource equipment and labor, driving up costs that will realign as it scales operations. Within that, acquisition integration issues (ultimately the cause of backlog headwinds) created public relations problems, with class action lawsuits alleging managerial misconduct. The question is whether management knew about scaling issues when pitching the buy to investors and, more importantly, whether they were aware of them ahead of the secondary stock offering.
Companies in This Article:
| Company | Current Price | Price Change | Dividend Yield | P/E Ratio | Consensus Rating | Consensus Price Target |
|---|
| H. B. Fuller (FUL) | $49.47 | -0.2% | 1.98% | 13.78 | Moderate Buy | $64.63 |
| FocalTherics (FOCL) | $4.30 | +2.6% | N/A | -4.17 | Hold | $7.75 |
| Cardinal Infrastructure Group (CDNL) | $21.14 | +0.1% | N/A | 38.53 | Moderate Buy | $49.25 |
Experience
Thomas Hughes has been a contributing author for InsiderTrades.com since 2019.
- Professional Background: Thomas Hughes is the Managing Partner of Passive Market Intelligence LLC, a market research platform he launched in 2023 with the mission: “We watch the market so you don't have to.” He has worked as a blogger, stock market commentator, and independent analyst since 2010 and has been actively involved in trading and investing since 2005.
- Credentials: He holds an Associate of Arts in Culinary Technology—training that honed his discipline, attention to detail, and ability to anticipate outcomes, all of which carry over into his work as a market analyst.
- Finance Experience: Thomas has been writing about finance and investing since 2011, when he discovered it could be more than a personal passion—it could be a profession. He’s been a contributing writer for InsiderTrades.com since 2019.
- Writing Focus: He specializes in the S&P 500, small-cap stocks, dividend and high-yield strategies, consumer staples, retail, technology, oil, and cryptocurrencies. His analysis blends chart-based technical setups with key fundamental insights, helping readers identify actionable trends.
- Investment Approach: Thomas takes a hybrid approach that combines technical analysis with deep fundamental research. He often writes about macroeconomic shifts, earnings trends, and sentiment-based trading signals.
- Inspiration: Thomas first became interested in stocks after attending a seminar on how to buy and sell your own shares. That event opened his eyes to the market's potential and sparked a lifelong interest in investing.
- Fun Fact: Thomas took up model railroading by accident a few years ago—and now he can’t stop running the rails.
- Areas of Expertise: Technical and fundamental analysis, S&P 500, retail and consumer sectors, dividends, market trends
Education
Associate of Arts in Culinary Technology
