Key Points
- Despite record insider selling at Rocket Lab, institutions, which own 72% of shares, have been net buyers for six consecutive quarters, signaling confidence.
- Analysts maintain a consensus Moderate Buy rating on Rocket Lab with a 75% Buy-side bias and more than 70% upside from the $60 support level.
- Rocket Lab's growth outlook rests on surging revenue, a $2.3 billion backlog, margin improvement, and the upcoming Neutron rocket launch expected by year's end.
Rocket Lab (NASDAQ: RKLB) insiders aren’t just selling in Q3, they are selling at the fastest pace on record, with sales logged by the CEO, CFO, COO, an SVP and a VP.
However, these sellers, unlike the average investor, earned their shares through share-based compensation awards. And they have incentive to sell—not only is the stock up 300% over the past five years, but portfolio diversification and the resulting tax burdens also weigh on their decision. The real question is whether anyone is buying the stock—and all signs point to yes.
Institutions are the most obvious, owning 72% of the shares and buying on balance for six consecutive quarters. Quarter-to-quarter activity has varied, rising and falling with the stock price but remaining bullish each period. Institutions provide a solid support base with technical support indicated near the $60 level.
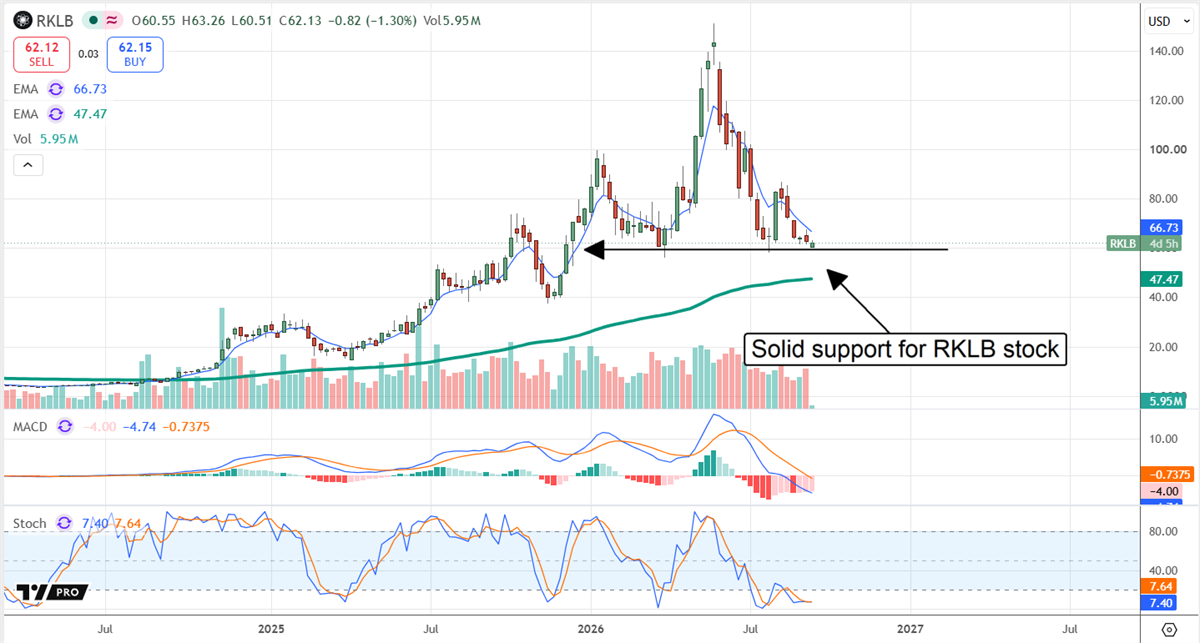
Analysts, who drive market sentiment, are also bullish on this stock. The 24 tracked rate the stock a consensus Moderate Buy, with a 75% Buy-side bias in the data and more than 70% upside relative to the critical support target around $60. The late-2026 trend includes steady price targets, increasing coverage, and firming sentiment, with the technical price floor aligned with the analyst range. The lowest target on record is $60.
Rocket Lab Has the Fuel to Launch Share Prices Higher in 2027
Reasons to buy Rocket Lab include its fast growing revenue, outperformance, backlog, margin improvements, and new technology. Revenue growth topped 60% in Q2, outpacing estimates on new contracts and deepening dependence on the Electron rocket system. It's made more than a dozen successful launches this year and continues to validate itself in the market’s eyes.
While Rocket Lab is still unprofitable, the increasing launch pace and ancillary services are driving margin improvement which, alongside the backlog, provide a clear runway for the next few years. The backlog topped $2.3 billion, enough for years of business, putting it on track for adjusted profits as soon as next year.
The new technology centers on the Neutron rocket system. It is a medium-duty system with an initial launch scheduled for this year, central to the growth and profitability outlook. Neutron will enable not only a faster launch pace, but also larger payloads with better operational metrics. A successful initial launch paves the way for Neutron’s commercialization and is likely to trigger stock price action.
Dilution is a risk, but a diminishing one, given the profitability outlook. The bad news is that the share count increased by 22% on average in Q2, but this is offset by the impact on the balance sheet. The balance sheet reflects ample liquidity, extremely low debt levels, and relatively unimpaired cash flow, with no red flags at this time. Cash and equity are likely to decline in upcoming quarters, but this is expected and not a problem as long as the company executes its strategy with minimal disruptions.
Rocket Lab Ignition Levers: Acquisitions, Expansions, and Growth Vectors
Rocket Lab has several catalysts in play to help drive its share price in the near and long term. These include acquisitions such as Iridium Communications, Motiv Space Systems, Mynaric AG, and Geost, LLC, which expand the company's offerings, increase vertical integration, and improve utility for clients. Collectively, these additions provide an operational satellite constellation, robotics expertise, and optical technology, setting the stage for Rocket Lab’s emergence as a comprehensive space service.
Expansions include the Global Hypersonic & Orbital Spaceport Technology. It is essentially a spaceport in a box, enabling sub-orbital and orbital launches from anywhere. Other catalysts include growth vectors such as the Flatellite system. Flatellites are compact, modular satellites built for efficient cargo space. They can be stacked on pallets, unlike bulky traditional satellites and provide a more efficient way to launch large space constellations. An open-ended government contract for Flatellites worth nearly $400 million in initial orders is part of the backlog.
Rocket Lab’s price action suggests it is preparing to take off. The market shows clear support along with signs of an impending momentum swing. The critical detail is the MACD convergence set in May. It reveals a strong, strengthening market likely to retest its existing high on a rebound, if not move up to set a new high. The only question is timing: how long the rebound takes to form, and the quicker, the better. As it stands, the most obvious catalysts are the early November earnings report and the delivery of Neutron to the launchpad, which is expected by year’s end.
Companies in This Article:
| Company | Current Price | Price Change | Dividend Yield | P/E Ratio | Consensus Rating | Consensus Price Target |
|---|
| Rocket Lab (RKLB) | $63.10 | +0.2% | N/A | -234.01 | Moderate Buy | $107.32 |
Experience
Thomas Hughes has been a contributing author for InsiderTrades.com since 2019.
- Professional Background: Thomas Hughes is the Managing Partner of Passive Market Intelligence LLC, a market research platform he launched in 2023 with the mission: “We watch the market so you don't have to.” He has worked as a blogger, stock market commentator, and independent analyst since 2010 and has been actively involved in trading and investing since 2005.
- Credentials: He holds an Associate of Arts in Culinary Technology—training that honed his discipline, attention to detail, and ability to anticipate outcomes, all of which carry over into his work as a market analyst.
- Finance Experience: Thomas has been writing about finance and investing since 2011, when he discovered it could be more than a personal passion—it could be a profession. He’s been a contributing writer for InsiderTrades.com since 2019.
- Writing Focus: He specializes in the S&P 500, small-cap stocks, dividend and high-yield strategies, consumer staples, retail, technology, oil, and cryptocurrencies. His analysis blends chart-based technical setups with key fundamental insights, helping readers identify actionable trends.
- Investment Approach: Thomas takes a hybrid approach that combines technical analysis with deep fundamental research. He often writes about macroeconomic shifts, earnings trends, and sentiment-based trading signals.
- Inspiration: Thomas first became interested in stocks after attending a seminar on how to buy and sell your own shares. That event opened his eyes to the market's potential and sparked a lifelong interest in investing.
- Fun Fact: Thomas took up model railroading by accident a few years ago—and now he can’t stop running the rails.
- Areas of Expertise: Technical and fundamental analysis, S&P 500, retail and consumer sectors, dividends, market trends
Education
Associate of Arts in Culinary Technology
