Key Points
- Matador Resources executives and directors purchased approximately 23,600 shares in Q3 2026, reinforcing the company's history of insider buying.
- Matador's third-quarter oil and natural gas revenue increased 51% year over year, while production grew 10%.
- Matador raised its annual dividend by nearly 17%, and analysts maintain a Moderate Buy consensus despite the stock's recent decline.
Matador Resources (NYSE: MTDR) is no stranger to InsiderTrades.com, as its executives, including founder, chairman, and CEO Joseph Foran, regularly buy shares. In 2026, the narrative is steady accumulation among leading executives, often on the open market in tandem with earnings reports. Buying can signal confidence in operations, cash flow, and value, which appears attractive for such a solid, dividend-paying stock. Trading at approximately 8.7x trailing earnings and 5x forward earnings, the market may be underestimating the cash-flow runway, which is the operative factor for this investment.
Matador Drives Growth, Raises Dividend
Volume, acquisitions, and price realization drove Matador’s strong Q3 results. Net oil and gas revenue of $1.22 billion rose more than 50% year over year (YOY), with volume up 10%, driving leverage throughout the report. Moving down, the company’s capital thrift and operational quality helped widen margins substantially, enabling improved cash flow and visibility. A 6% YOY decline in cost per completed foot reflects quality improvement, and management expects that cost to hold steady through year’s end.
Visibility improved through an improved asset base, capacity expansion, and reserves, which grew 16% in the quarter. Together, they enable improved near-term production, volume gains, and an extended operational runway. Looking ahead, the company faces risks, but reserves suggest an eight- to 10-year runway that can be extended through exploration and acquisition. Within this, cash flow was solid, enabling further debt reduction and the subsequent improvements it brings.
Matador is an energy company focused on natural gas, shale, and unusual formations, but it's also a cash-flow machine intended to pay investors. Management has it set up to pay an approximate 3.3% yield as of early November, and signaled confidence with another dividend increase. The eighth in five years, MTDR pays about 25% of its earnings as dividends, which is highly sustainable and provides room for future increases as well as a cushion should financial results begin to deteriorate. The likely outcome, however, is that Matador continues to execute its strategy, including its dividend and distribution increases.
Matador’s cash flow also supports share buybacks, which incrementally reduce the share count. Investors should focus on the company’s equity, which continues to grow despite capital returns. Equity rose 8.5% year-to-date, supported by receivables and liquid assets.
Bullish Analysts Respond With Caution: Forecast Double-Digit Upside
Analysts are bullish on this stock and provide a strong conviction, with 16 tracked by MarketBeat, high for such a small company. They rate the stock a consensus Moderate Buy, have a 75% Buy-side bias, and have made mixed price-target adjustments recently. Consensus forecasts about 35% upside as of early November, aligning with the top of the current trading range, with high-end targets at fresh highs.
A risk is that analysts temper their forecasts as the year progresses, as some recent target cuts demonstrate. Fear centers on natural gas pricing, but demand is also in play. Liquefied natural gas (LNG) demand is growing, and Matador expects improved natural gas realizations from contracts with Gulf Coast liquefaction companies beginning in 2027. In this environment, natural gas prices may remain volatile, although rising demand from AI data centers, manufacturing, and power generation could support volumes over time.
Institutions Signal Confidence in Matador Resources
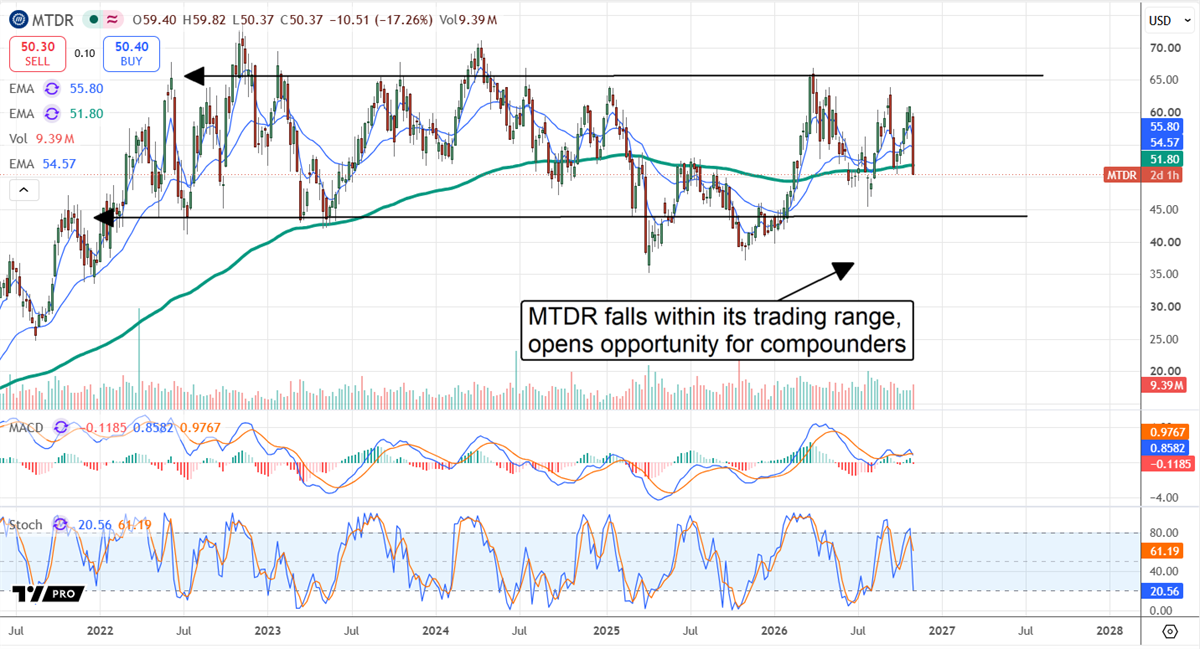
Institutional buying activity is another confidence signal for investors. This group owns more than 90% of the shares, highlighting broad institutional interest, and has bought more shares than it sold over the past year. Such ownership may support investor confidence, but that does not mean lower prices aren't possible. MTDR has plenty of bullish catalysts but has traded within a range for years. The Q3 release failed to trigger upward movement; the opposite, in fact, and MTDR could test support at the lower end of its trading range.
The market may be getting it wrong by treating Matador as a single-play maverick and valuing it at such a low price-to-earnings multiple. It’s a small but growing and diversified operation, including substantial midstream operations. The midstream business provides visible, high-margin cash flow insulated from natural gas prices, supporting financial strength. The flip side, however, is the inherent risk that the market gets it right. CEO Joseph Foran aims to keep the company independent, and it may not warrant a higher multiple because the market purposefully prices it with no premium, expecting no future buyouts.
The potential opportunity in Matador Resources centers on several developments management highlighted in the Q3 conference call. Large-scale acquisitions in the Delaware Basin provide numerous drilling opportunities, while the now-fully operational Hugh Brinson Pipeline has significantly improved natural gas price realizations. Now served with better access to the Gulf Coast and other higher-priced markets, the company also benefits from better-than-expected drilling results, which helped to extend the production runway and asset monetization. More importantly, the improved business supports an outlook for accelerated balance sheet deleveraging, improved cash flow, and capital returns.
Companies in This Article:
| Company | Current Price | Price Change | Dividend Yield | P/E Ratio | Consensus Rating | Consensus Price Target |
|---|
| Matador Resources (MTDR) | $49.87 | -1.0% | 3.01% | 8.60 | Moderate Buy | $68.50 |
Experience
Thomas Hughes has been a contributing author for InsiderTrades.com since 2019.
- Professional Background: Thomas Hughes is the Managing Partner of Passive Market Intelligence LLC, a market research platform he launched in 2023 with the mission: “We watch the market so you don't have to.” He has worked as a blogger, stock market commentator, and independent analyst since 2010 and has been actively involved in trading and investing since 2005.
- Credentials: He holds an Associate of Arts in Culinary Technology—training that honed his discipline, attention to detail, and ability to anticipate outcomes, all of which carry over into his work as a market analyst.
- Finance Experience: Thomas has been writing about finance and investing since 2011, when he discovered it could be more than a personal passion—it could be a profession. He’s been a contributing writer for InsiderTrades.com since 2019.
- Writing Focus: He specializes in the S&P 500, small-cap stocks, dividend and high-yield strategies, consumer staples, retail, technology, oil, and cryptocurrencies. His analysis blends chart-based technical setups with key fundamental insights, helping readers identify actionable trends.
- Investment Approach: Thomas takes a hybrid approach that combines technical analysis with deep fundamental research. He often writes about macroeconomic shifts, earnings trends, and sentiment-based trading signals.
- Inspiration: Thomas first became interested in stocks after attending a seminar on how to buy and sell your own shares. That event opened his eyes to the market's potential and sparked a lifelong interest in investing.
- Fun Fact: Thomas took up model railroading by accident a few years ago—and now he can’t stop running the rails.
- Areas of Expertise: Technical and fundamental analysis, S&P 500, retail and consumer sectors, dividends, market trends
Education
Associate of Arts in Culinary Technology
